Inventory requirements in Germany: rules & obligations explained
Whether GmbH, AG or registered merchant: for many companies in Germany, the inventory is required by law. This article explains who is obliged to take inventory, which legal requirements apply and how digital inventory software makes compliance with the inventory obligation considerably easier.
Inventory obligation at a glance
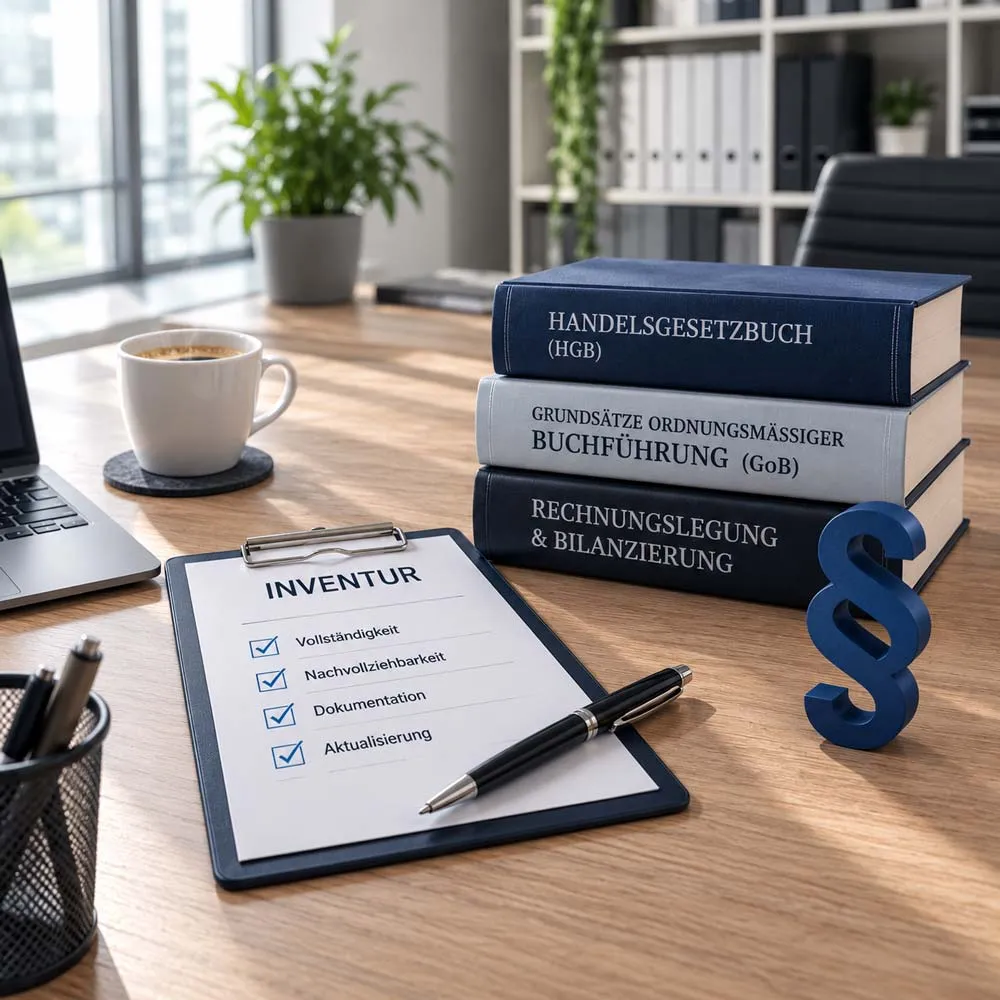
The inventory is required by law for many companies in Germany. It serves to capture the entire assets and liabilities of a company completely and forms the basis for proper bookkeeping as well as the annual financial statements.
In doing so, companies must:
- capture all assets and liabilities completely
- document the results traceably
- comply with legal retention obligations
- update their inventory data regularly
Digital inventory software makes compliance with these legal requirements considerably easier while reducing the organisational effort.
What is the inventory obligation?
The inventory obligation describes the legal obligation of companies to capture their assets and liabilities completely on a specific reference date. The result of this stocktaking is referred to as the inventory and forms the basis for the balance sheet.
The inventory is an essential part of proper bookkeeping and ensures that companies always have a correct overview of their economic situation.
Among other things, the following are captured:
- fixed assets (machines, vehicles, IT devices, office equipment)
- current assets (warehouse stock, raw materials, consumables)
- receivables
- liabilities
- liquid funds
Who is obliged to take inventory?
The inventory obligation affects a large proportion of German companies. In particular, the following must carry out an inventory:
- merchants under the German Commercial Code (HGB)
- corporations (e.g. GmbH or AG)
- companies with a statutory bookkeeping obligation
- commercial partnerships
- many larger commercial businesses
Companies that prepare their annual financial statements according to the provisions of commercial law must also carry out a proper inventory regularly.
Which legal foundations apply?
The inventory obligation arises in particular from the German Commercial Code (HGB). It stipulates that companies must:
- carry out an inventory at the start of their business activity
- capture all assets and liabilities at the end of each financial year
- document their inventory data completely
- retain the documents in an audit-proof manner
The aim of these legal requirements is a traceable and transparent company balance sheet.
What has to be captured during an inventory?
As part of the inventory, all assets and liabilities are documented. These include, for example:
Fixed assets
- machines
- production installations
- vehicles
- computers and IT hardware
- furniture and office equipment
Current assets
- stocks of goods
- raw materials
- spare parts
- consumables
Financial values
- bank balances
- cash holdings
- receivables
- liabilities
Only if all items are documented completely does the inventory fulfil its legal purpose.
Which types of inventory are there?
Depending on company size and organisation, different inventory procedures are used.
Key-date inventory
The classic inventory takes place on a defined balance sheet date.
Timely inventory
The stocktaking can take place within a legally permissible time window before or after the balance sheet date.
Permanent inventory
All stock changes are documented continuously. This often eliminates the need for a complete physical stocktaking at the end of the year.
Sample inventory
Under certain conditions, companies may use statistical procedures and do not have to count all assets individually.
Which type of inventory is permissible depends on the legal requirements as well as the organisation of the company.
Typical challenges during the inventory
In many companies, the inventory is still carried out using Excel lists or paper-based checklists. This often leads to problems such as:
- incomplete inventory lists
- duplicate records
- missing responsibilities
- high manual capture effort
- transfer errors
- a lack of transparency about locations
- time-consuming rework during the preparation of the annual financial statements
As company size grows, this effort increases considerably.
Why digital inventory software is becoming ever more important
Digitalisation is also changing inventory processes. Modern inventory software helps companies to comply with legal requirements more easily while significantly reducing the workload.
Typical functions are:
- digital inventory management
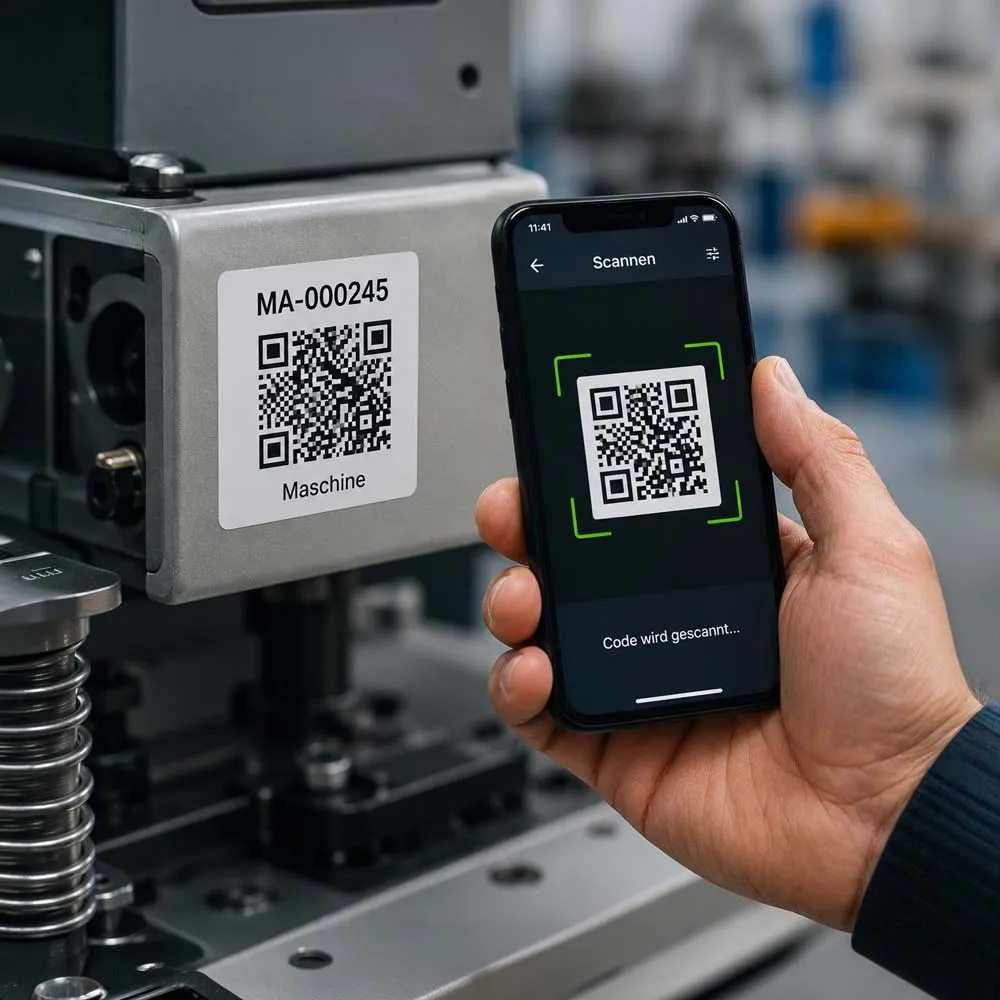
- QR code or barcode labelling
- mobile inventory capture via smartphone or tablet
- automatic documentation of all changes
- location management
- responsibilities per inventory item
- inventory history
- evaluations and reports
- audit-proof documentation
This makes up-to-date inventory data available at all times.
How INVENTIRE supports compliance with the inventory obligation
Digital solutions such as INVENTIRE help companies to carry out their inventory efficiently and in compliance with the law. With central inventory management, all assets can be labelled clearly and captured mobile.
The software supports, among other things:
- QR code and RFID-based inventory management
- digital asset management
- mobile inventories
- transparent documentation
- easy tracking of changes
- central management of multiple locations
This considerably reduces the organisational effort while increasing the quality of the inventory data.
Advantages of a digital inventory
Companies benefit in several ways from digital inventory processes:
- considerable time savings compared to manual inventories
- fewer errors during data capture
- up-to-date inventory data at all times
- better transparency over all operating resources
- easier collaboration across multiple locations
- audit-proof documentation
- faster preparation of the annual financial statements
Digital inventories not only create legal certainty but also increase efficiency throughout the entire company.
Conclusion
The inventory obligation is far more than a legal formality. It forms the basis of proper bookkeeping and a correct annual financial statement.
Those who continue to organise their inventory with Excel or paper risk unnecessary extra effort, errors and a lack of transparency.
Modern inventory software helps companies to reliably comply with legal requirements, standardise processes and make the entire inventory process significantly more efficient.
The digitalisation of the inventory is therefore not only an organisational improvement but an important step towards future-proof company administration.